


Top Business Checking Accounts for LLCs: Fees, Features, and How to Select the Best for Your Business
For years, institutional banks and credit unions largely operated the same way. Business checking accounts were built around paper checks, in-branch visits, and phone calls for basic account support. While these systems may feel familiar, they're outdated and built around workflows that made sense decades ago, but no longer fit the needs of modern businesses. In reality, many of the limitations associated with traditional business banking persist more out of habit than necessity.
Modern banking platforms like Slash are built to eliminate these shortcomings by rethinking how businesses manage their finances.¹ Why use checks when digital payments can be faster and more secure? Why don't cards automatically capture receipts and transaction details? Why do international payments still come with delays and hidden fees? Why isn't accounting fully automated? Instead of accepting outdated processes, Slash delivers a digital-first banking platform designed to reduce costs, automate workflows, and give LLCs true financial control.
In this guide, we'll evaluate the best business checking accounts for LLCs, compare how their fees and features stack up, and clarify what to prioritize when selecting an account that aligns with your modern business needs. We'll also highlight how Slash goes beyond the capabilities of legacy banks, with more flexible payment options, real-time visibility into funds, centralized financial controls, and more.
Key takeaways:
- Brex’s treasury yield is tiered by balance. Accounts up to $500,000 earn about 3.62%, while balances of $20 million or more reach 3.97%.
- In a similar fashion, Bluevine’s 3.0% APY sits behind the $95 a month Premier plan. The Standard plan pays 1.3%, and lower tiers only pay interest on the first $250,000 of your balance.
- Transaction caps are where traditional accounts can get expensive. U.S. Bank’s Gold package covers 350 free transactions a month and charges $0.45 for each one after, while Chase Platinum includes only four free wires per statement cycle before charging up to $40 apiece.
- Chase waives its $95 fee at $100,000 and Capital One waives $35 at $25,000, while Ramp and Brex require $25,000 and $50,000 respectively just to open an account.
- The American Express Business Checking debit card earns 0.5x Membership Rewards points, or one point per $2 spent. There’s also no overdraft protection, so transactions that exceed your balance are declined rather than covered.
What Business Checking Accounts Should Come With
Business checking accounts once offered a fairly limited set of features. Most accounts were tied to a basic debit card, came with standard FDIC insurance coverage, and supported only a handful of electronic funds transfer (EFT) methods.
Today, businesses can expect more from their bank accounts to help manage finances. Modern business checking accounts may include business banking features such as:
- Sweep-network FDIC insurance: Standard FDIC insurance covers up to $250,000 per depositor, per bank. With insured cash sweep networks, like the Column N.A. Sweep Network used by Slash, funds can be distributed across multiple banks to provide millions of dollars in FDIC coverage while keeping balances accessible.²
- Charge or debit cards: Debit cards allow businesses to spend directly from their account balance, while charge cards are an alternative that allow short-term borrowing, with balances paid in full at the end of each billing cycle.
- Accounting integrations: Most financial platforms allow users to connect their banking with third-party accounting apps. For example, Slash can sync transaction data with QuickBooks Online, Xero, NetSuite, and Sage Intacct.
- Virtual accounts: Some providers offer virtual or segmented accounts that allow businesses to separate funds for better cash flow management. Slash makes it possible for users to organize their funds into distinct pools, improving visibility into account-specific trends and transactions.
- Automation capabilities: Modern business accounts and cards can automatically collect transaction details, schedule and execute payments, route approvals, and export financial data to accounting platforms to support reconciliation, reporting, and audit preparation. This is where automation in banking delivers measurable value.
Evaluating Different Business Banking Options for LLCs
Not all business checking accounts work the same way, even when they appear similar at first glance. The section below breaks down how leading providers compare across fees, features, and overall flexibility for LLCs:
Slash
Slash is a digital-first business banking platform designed for companies seeking greater control over cash flow, payments, and spend management. The Slash platform supports configurable virtual accounts, making it easier to separate entities, departments, or specific cash flows from a single dashboard. It combines robust digital banking with tools that simplify daily operations.
Here’s what you need to know about Slash:
- Fees and minimums: Free business checking with no minimum balance requirements. Unlimited free domestic transfers and up to 2% cashback on eligible purchases are available with the Pro Plan for $25 per month.
- Diverse payment rails: Free, unlimited ACH transfers, domestic wires, and outgoing FedNow/RTP real-time payments, with international transfers available via wire to 180+ countries or through USD-pegged stablecoins like USDT and USDC.⁴ Slash also supports quite a few local rail outside the United States, including Pix, SEPA, and Faster Payments.
- Cashback and cards: Unlimited virtual charge cards earning up to 2% cashback on eligible company spending.
- Savings and insurance: Millions in FDIC insurance through the Column N.A. sweep network for business accounts.
- High-yield treasury accounts: Earn up to 4.06% annualized yield through money market funds from BlackRock and Morgan Stanley.⁶
- Eligibility: At this time, Slash does not support sole proprietorships.
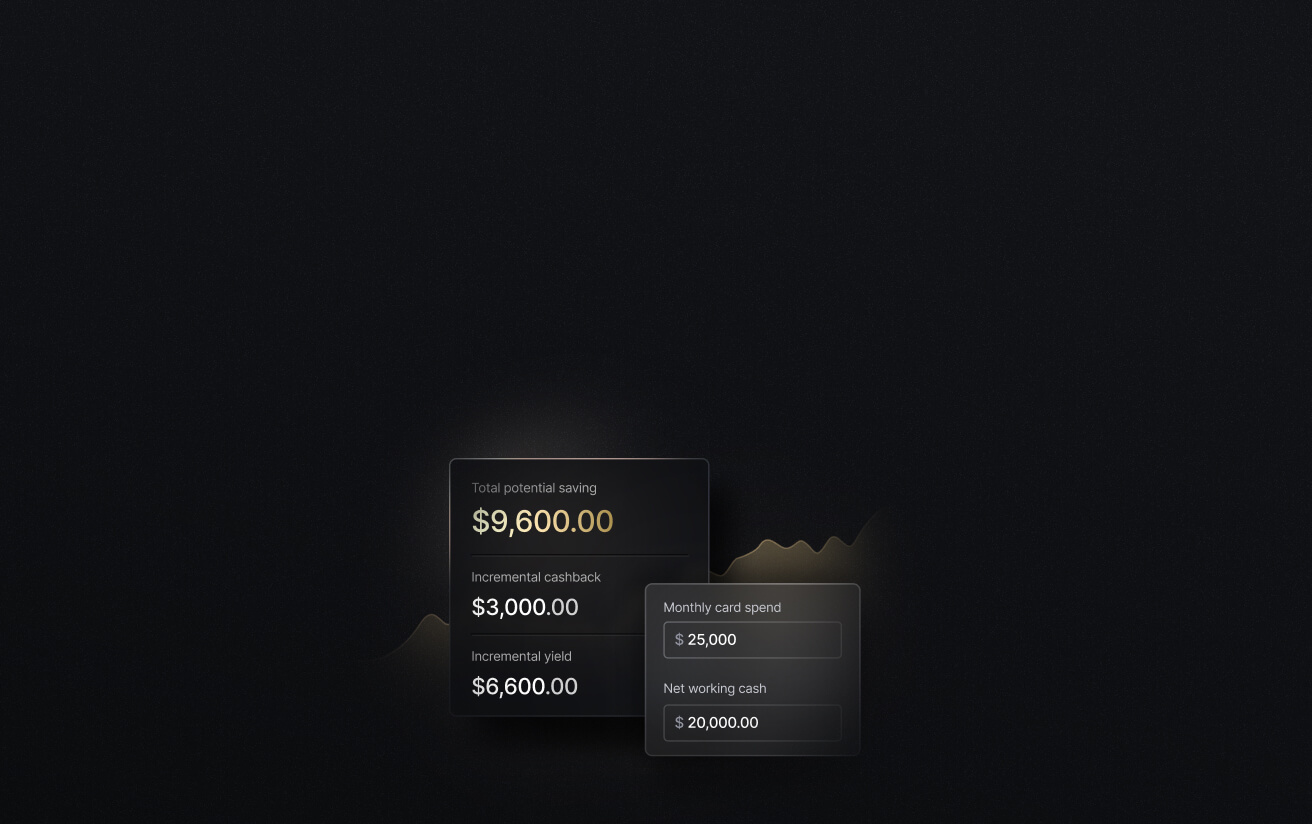
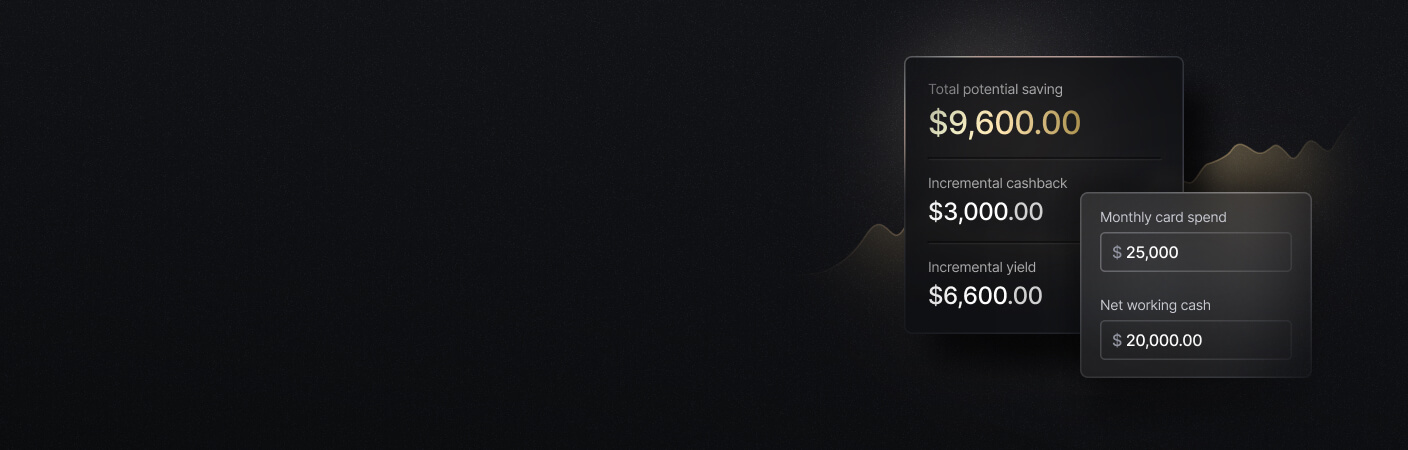
See the ROI behind your spend
Use this calculator to understand impact, then manage and track it all in Slash.
Chase Platinum Business Checking
Chase offers traditional business checking accounts with in-branch access and a wide range of services, though many features depend on account tier and minimum balance requirements. Their Platinum Business Checking Account isn’t the cheapest, requiring either monthly fees or a high minimum balance that locks up capital.
Here’s what you need to know about the Chase Bank Platinum Business Checking Account:
- Fees and minimums: $95 monthly maintenance fee or $100,000 minimum balance. Fee waivers may apply based on activity and balances. Incidental fees: Only four free wire transfers per statement cycle, while additional wires cost up to $40 each. Same-day ACH and real-time payments come with added fees.
- Invoice tools: Built-in invoicing tools through the Chase app and online portal.
- Cash deposits: Up to $25,000 in-branch cash deposits per statement period at no charge
Ramp
Ramp prioritizes charge cards over traditional debit cards and offers a digital-first platform with automation and integration capabilities. However, Ramp gates access behind a steep minimum balance requirement at account opening, immediately excluding early-stage LLCs and businesses without substantial cash reserves already on hand.
Additionally, while Ramp advertises their charge card as “up to 1.5%”, the more honest range is “0% to 1.5%.” As NerdWallet learned in mid-2026, business can land anywhere in that range based on Ramp’s decision-making process, and you’re not guaranteed rewards at all.
Here’s what you need to know about the Ramp Business Account:
- Fees and minimums: Requires $25,000 minimum balance at account opening. Plans range from free to $15/month/user, as well as a custom-quoted Enterprise tier.
- Cashback structure: Rewards are capped at 1.5% cashback, though they can fall much lower.
- Travel tools: Enforces travel policies at booking, reconciles expenses automatically, and finds extra savings.
- Automations: Supports scheduled payments, approval workflows, and integrations with accounting software and ERPs
American Express National Bank
American Express National Bank (AENB) is the business banking arm of American Express. Despite Amex's long history in banking, AENB is a relatively recent entrant to business checking, launching its account in October 2021. However, the debit card's rewards structure is surprisingly weak for an Amex product, earning a fraction of what cardholders typically expect and falling far below competitors' cashback rates.
Here’s what you need to know about the AENB Business Checking Account:
- Membership Rewards: Debit card earnings limited to just 0.5x points per dollar (one Membership Rewards point for every $2 spent), which is significantly lower than Amex's credit and charge card offerings and well below competitor cashback rates.
- Overdraft policy: No overdraft protection available; transactions exceeding your balance are declined rather than covered
- Fees and minimums: No monthly service fee and no minimum balance requirement
U.S. Bank
The U.S. Bank Gold Business Checking Package is offered in two versions: traditional and interest-bearing. While it includes some free transactions, the account imposes transaction limits that penalize businesses with high volumes, charging additional fees once you exceed the monthly cap. Additionally, U.S. Bank lacks the automated expense tracking and real-time financial visibility that modern fintech platforms provide.
Here’s what you need to know about the U.S. Bank Gold Business Checking Package:
- Transaction limits: Only 350 free transactions per month, while additional transactions cost $0.45 each. This can add up quickly for active businesses.
- Fees and minimums: $20 monthly service fee unless you maintain a $10,000 average balance.
- Interest rates: Interest-bearing versions of the account earn just 0.01% APY, which is well below most competitors.
Bluevine
Bluevine offers a small business checking account with interest-earning capabilities that vary by plan. However, accessing competitive interest rates requires paying a steep monthly fee that can quickly erode the value of higher yields, making the account financially viable only for businesses with large balances.
Here’s what you need to know about the Bluevine Business Checking Account:
- Interest structure: Competitive 3.0% APY requires $95/month Premier plan, while the Standard plan earns just 1.3% APY.
- Balance limits: You only earn interest on balances of up to $250,000 on lower-tier plans, while Premier increases cap to $3 million.
- Working capital: Bluevine offers working capital lines of credit of up to $250k, with rates as low as 7.8% (as of November 2026).
- Transfer fees: $15 fee for external wire transfers at the standard plan, with discounts on higher plans. ACH transfers are free, but take one to three business days.
Brex
Brex is designed for highly capitalized startups and larger businesses with complex financial needs, offering treasury features that provide higher yields at larger balances. However, the platform may be inaccessible for most LLCs, requiring significant capital and operational scale that excludes most small businesses from consideration.
Here’s what you need to know about the Brex Business Checking Account:
- Target customer profile: Restricted to startups with at least $50,000 in a business checking account and larger companies that earn at least $400k a month. As a result, most LLCs and small businesses don't qualify.
- Yield structure: Treasury yields favor large accounts. Balances up to $500,000 earn approximately 3.62% versus 3.97% for accounts holding $20 million or more, as of November 2026.
- FDIC coverage: Up to $6 million in FDIC insurance through Brex Vault.
Capital One Enhanced Business Checking
Capital One's Enhanced Business Checking is a standard business checking account designed for small to mid-sized businesses that want access to traditional banking services, including branches and a large ATM network. However, Capital One falls short on digital capabilities, offering limited automation and integration features compared to purpose-built fintech solutions.
Here’s what you need to know about Capital One Enhanced Business Checking:
- Fees and minimums: $35 monthly service fee unless you maintain a $25,000 minimum balance.
- International wires: Incoming wires cost $15, while international outgoing wires cost $40 to $50 depending on the currency. Domestic outgoing wires are free for your first five in a month, then $25 after.
- ATM access: Fee-free cash withdrawals and deposits through the Allpoint ATM network.
Opening an Online Business Bank Account: What Should You Consider When Selecting One?
LLCs come in many different structures and sizes, so there’s no one-size-fits-all approach when choosing a banking partner. That said, every LLC should prioritize two core considerations: whether the banking system simplifies accounting and tax preparation, and whether it saves the business time and money. Below are key factors to consider when comparing different business bank accounts:
Monthly fees and minimums
Many banks charge monthly service fees or require minimum balances to avoid them. When evaluating options, look beyond the advertised monthly fee and review the full fee structure, including how minimum balance requirements compare to your LLC's typical cash reserves. Slash business bank accounts have no minimum balance requirements and no monthly fees on the free plan.
Transaction limits and volume
Some business accounts limit the number of transfers or withdrawals allowed before additional fees apply. While domestic ACH transfers are often inexpensive, providers may offset this by charging higher fees for wire or international payments. With the $25/month Slash Pro plan, businesses can send unlimited domestic ACH, wire transfers, and real-time payments over RTP and FedNow without per-transaction fees.
Online banking access
While most banks offer online portals, not all provide the full functionality of a modern business banking platform. In some cases, businesses may need to call or email their bank to confirm transfer details or wait for mailed statements to review transaction activity. Slash provides real-time visibility across accounts, cards, and payments, allowing businesses to monitor their cash flow and transaction details directly from the dashboard.
FDIC insurance and security
Today, account holders can access FDIC insurance well beyond the standard limits. Slash partners with Column N.A., which uses an insured cash sweep network to increase the total amount of FDIC insurance available by spreading deposited funds across multiple banks. Slash is also a SOC-2 Type II certified financial services provider, reinforcing our commitment to protecting customer financial data.
How to Open a Business Bank Account: Key Requirements You Should Know
Opening a business bank account typically requires a mix of personal identification and business documentation. While exact requirements vary by bank and business structure, most financial institutions will ask for the following information:
Personal identification
Banks need to verify the identity of the business owner or authorized signers. This usually means you’ll provide a Social Security Number (SSN) or another government-issued ID, such as a passport or driver's license, as well as personal contact details, including name, phone number, and email address.
Business entity information
Most financial institutions also require basic details about your business to confirm its legal status:
- Legal business name as registered with the state
- Business address, either physical or mailing
- Type of business entity, such as a sole proprietorship, partnership, LLC, or corporation
- Business registration certificate or state filing confirming the business is officially registered
Federal and tax documentation
Tax identification is required to support reporting and compliance. During your application, you'll likely need your LLC's Employer Identification Number (EIN) issued by the IRS. In some cases, sole proprietors without employees may be allowed to use an SSN instead, depending on the bank's policies.
Formation and governing documents
Depending on your business structure, banks may request documentation that outlines ownership and authority, including:
- Articles of Incorporation
- Corporate bylaws that define governance and decision-making authority
- LLC operating agreements that describe ownership and responsibilities
- Partnership agreements showing who is authorized to act on behalf of the business
- Additional documents that help confirm business ownership or structure, if required
Licenses and certificates
Some banks may also request proof that your business is authorized to operate by asking for a valid business license. Requirements may vary depending on your state or local jurisdiction.
When Should a New LLC Open Its Business Bank Account?
In short, you should open it as soon as the LLC legally exists and has an EIN, ideally before the first sale or expense. New companies are forming at a record pace – the U.S. Census Bureau's Business Formation Statistics showed 5,671,836 business applications in 2025, which was the highest annual total in the series, and applications from January through August 2026 were running more than 13% ahead of the same months in 2025. Every one of those new businesses faces the same early choice about where its money will live.
Waiting creates problems that are hard to undo. Formation fees, software, and early client payments that run through a personal account have to be untangled later for bookkeeping and taxes. Mixing funds can also weaken the liability protection that made you form an LLC in the first place.
It’s wise to have your formation paperwork ready before you apply: articles of organization, your EIN confirmation letter from the IRS, and an operating agreement that names who can sign for the business. Banks also ask for identifying information on each owner of 25% or more and on one person who controls the company. Fund the account with the owners' initial contributions and record them as capital, so your books start clean from day one.
Make the Switch to Slash for Business Banking
Choosing the right business checking account for your LLC means looking beyond basic banking services and evaluating how your account can actively support your operations. It's important to consider how an account handles fees, supports online access, and reduces manual work as your operations become more complex.
Slash removes many of the structural constraints that can complicate day-to-day banking for LLCs. Without minimum balance requirements or per-transaction limits, businesses have more flexibility in how and when they move money, manage spending, and allocate cash across accounts. A simpler fee structure also reduces the need to track thresholds or avoid incidental charges.
At the same time, built-in automation helps handle routine financial tasks that are often manual with traditional banks, from payment workflows to transaction tracking. Taken together, these features make Slash a practical option for LLCs that want a business checking account designed to support ongoing operations, rather than one that adds administrative overhead as the business grows.
Slash comes with plenty of features that we haven’t touched on, including:
- Global USD: The Slash Global Account is designed as an alternative for foreign founders who want access to USD without forming a US entity.³ Accounts are backed on Bridge by a balance held in USDC, which is designed to maintain a one-to-one value with the US dollar.
- Working capital financing: Access short-term financing with flexible 30-, 60-, or 90-day repayment terms to help bridge cash flow gaps.⁵
- Invoicing: With Slash’s invoicing and bill pay features, users can send customized invoices, collect payments, and manage vendor bills all in the same place.
- MCP connections for agents: The Model Context Protocol is an open standard for connecting AI agents to software tools. Through MCP, agents can connect to Slash directly.
- Separate virtual accounts: Create multiple business bank accounts to silo cash flows by project, department, or client with real-time analytics across each of them.
Apply in less than 10 minutes today
Join the 10,000+ businesses already using Slash.
Frequently Asked Questions
Can I use my personal bank account for my LLC?
While it can be legally possible for single-member LLCs, using a personal account can blur the line between personal and business finances. That in turn complicates accounting and tax preparation, and weakens your liability protection. Most LLCs benefit from keeping business transactions in a dedicated business checking account.
Should You Put Business Expenses on a Personal Credit Card?

Is it better to open a business bank account online or in person?
Online accounts are often faster to open and tend to offer more automation and lower fees, while in-person accounts may be useful if you need branch access or cash services. The better option depends on how your LLC handles payments, deposits, and day-to-day banking.
How do transaction limits affect which bank account is best for an LLC?
Transaction limits can lead to unexpected fees as payment volume grows, especially for businesses that send frequent transfers or wires. Accounts with higher or unlimited transaction allowances are generally better suited for LLCs with active cash flow and recurring payments.


